2 Liquidity and Solvency
This section introduces two fundamental concepts in banking: liquidity and solvency. Although both are essential to a bank’s financial health, they refer to different aspects of its balance sheet. Consider the following simplified example.
| Assets (Uses of Funds) | Amount | Liabilities and Equity (Sources of Funds) | Amount |
|---|---|---|---|
| Cash | €15 | Deposits | €100 |
| Loans | €95 | Equity Capital | €10 |
| Total | €110 | Total | €110 |
- Liquidity refers to a bank’s ability to meet its immediate payment obligations using cash and other assets that can readily be converted into cash. In this example, the bank has €15 in cash available to meet deposit withdrawals. Its €95 in loans, by contrast, are generally illiquid: a bank cannot normally demand immediate repayment of a ten-year loan that it has only just issued.
- Solvency refers to whether the value of a bank’s assets is sufficient to cover its liabilities. It is reflected in the bank’s equity capital. Because the bank has €10 in positive equity capital, it is solvent on the basis of the asset values shown.
The following accounting identity always holds:
\[ \text{Equity Capital}=\text{Assets}-\text{Liabilities} \]
Thus, equity capital is the difference between the value of a bank’s assets and the value of its liabilities. Conceptually, it is the residual value that would belong to shareholders if the bank could sell all its assets at their stated values and use the proceeds to repay all its liabilities.
Four points are especially important:
- Equity capital is not cash. It is not a pile of money in a vault or a reserve balance held in a particular account. It is the residual claim recorded on the balance sheet.
- Equity capital belongs to shareholders. It represents the portion of the bank’s asset value attributable to its owners rather than its depositors or other creditors.
- Equity capital can be increased through external investment or retained earnings. A bank may raise additional equity from investors or retain profits instead of distributing them as dividends.
- Negative equity capital indicates insolvency. If the value of assets falls below the value of liabilities, the bank is insolvent. Insolvency is not necessarily the same as entering a formal bankruptcy proceeding.
Liquidity and solvency are conceptually distinct, but they can interact—and reinforce each other—during a banking crisis.
2.1 Examples
2.1.1 1. A Solvent Bank with Low Liquidity
| Assets (Uses of Funds) | Amount | Liabilities and Equity (Sources of Funds) | Amount |
|---|---|---|---|
| Cash | €1 | Deposits | €100 |
| Loans | €149 | Equity Capital | €50 |
| Total | €150 | Total | €150 |
This bank is highly solvent: its assets exceed its deposit liabilities by €50. Nevertheless, it holds only €1 in cash against €100 in deposits. If depositors suddenly demand substantial withdrawals, the bank may be unable to make the required payments immediately, even though the value of its assets is sufficient to cover its liabilities.
The problem is that being solvent does not necessarily mean being liquid. Loans may generate sufficient repayments over time without being readily convertible into cash today.
2.1.2 2. A Highly Liquid Bank with a Solvency Problem
| Assets (Uses of Funds) | Amount | Liabilities and Equity (Sources of Funds) | Amount |
|---|---|---|---|
| Cash | €50 | Deposits | €149 |
| Loans | €100 | Equity Capital | €1 |
| Total | €150 | Total | €150 |
This bank has €50 in cash, giving it substantial capacity to meet immediate withdrawals. However, it has only €1 in equity capital, so even a small loss on its loans could render it insolvent.
Suppose loan values fall from €100 to €98 because of defaults. Total assets become:
\[ 50+98=148 \]
Liabilities remain at €149. Therefore, equity capital becomes:
\[ 148-149=-1 \]
The bank now has negative equity capital and is insolvent.
A large cash balance should not be confused with overall financial soundness. A bank may have enough cash to meet immediate payments while still being vulnerable to losses that exceed its equity capital.
The central distinction is:
- Solvency: Are the bank’s total assets worth enough to cover its liabilities?
- Liquidity: Can the bank obtain the cash needed to meet its short-term payment obligations when they come due?
2.2 The Relationship Between Liquidity and Solvency
2.2.1 1. Doubts About Solvency Can Trigger a Liquidity Crisis
If depositors believe that a bank may be insolvent, they may fear that it will eventually be unable to repay everyone. To avoid potential losses, they may rush to withdraw their deposits, creating a bank run.
Large, simultaneous withdrawals can rapidly exhaust the bank’s cash and other liquid assets. Normally, a bank facing a temporary shortage of cash might borrow in financial markets. But if other banks and investors also doubt its financial condition, they may refuse to lend. The bank can then face a severe liquidity crisis.
The key mechanism is that concerns about solvency can create an immediate liquidity problem—even before insolvency has been conclusively established.
2.2.2 2. A Liquidity Crisis Can Lead to Insolvency
A bank facing heavy withdrawals may be forced to sell assets quickly to raise cash. Under distressed market conditions, those assets may have to be sold at a substantial discount.
For example, suppose an asset with a book value of €100 can be sold for only €70. The sale generates a €30 loss, reducing the bank’s equity capital. If such losses are sufficiently large, an initially solvent bank may become insolvent.
This illustrates how a liquidity problem can turn into a solvency problem. Although liquidity and solvency are different concepts, banking crises can produce a self-reinforcing interaction between them.
2.3 Measuring Solvency: Why Equity Capital Can Be Difficult to Assess
The definition of equity capital is straightforward, but measuring it accurately can be difficult because the value of a bank’s assets is often uncertain. In particular:
- Banks may overstate asset values. A troubled bank has an incentive to report optimistic asset valuations, making its equity capital appear larger than it really is.
- External auditors may fail to prevent overvaluation. Auditors are expected to assess the reliability of financial statements, but their judgments may be affected by incentives, including a desire to retain clients.
- Reported book equity may therefore be misleading. A bank may publish accounts showing positive equity capital even when the economic value of its assets is insufficient to cover its liabilities. Depositors, investors, and regulators may consequently treat reported capital figures with skepticism.
In short, assessing solvency depends critically on asset valuation. Information asymmetries and possible misreporting make the true financial position of a troubled bank difficult for outsiders to determine.
In principle, a central bank acting as the lender of last resort can provide emergency liquidity assistance to a bank that is solvent but temporarily illiquid. The central challenge, however, is determining whether the bank is genuinely solvent. Providing liquidity to a bank that is already insolvent may merely postpone the resolution of its losses and potentially shift costs to the public sector.
Example: The Irish banking crisis of 2008. On September 29, 2008, Irish banks sought government liquidity support, arguing that they were fundamentally sound and faced only temporary funding difficulties. The Irish government responded by guaranteeing almost all of their liabilities. The banks were subsequently found not to be fundamentally solvent, and honoring the guarantee imposed enormous costs. The episode illustrates the dangers of mistaking a solvency problem for a temporary liquidity shortage.
2.4 Book Value and Market Value of Equity
2.4.1 1. Book Value of Equity
The book value of equity is the difference between the values of assets and liabilities reported in a bank’s accounting statements:
\[ \text{Book Equity}=\text{Book Value of Assets}-\text{Book Value of Liabilities} \]
It is important not to interpret equity capital as cash that has been set aside. When regulators require a bank to increase its capital, they are not asking it to keep an additional pile of idle cash. Rather, a higher equity share means that shareholders absorb a larger share of potential asset losses before creditors are affected.
Illustrative example: A higher equity-to-assets ratio
Suppose a bank initially has the following balance sheet (amounts in hypothetical monetary units):
| Assets | Amount | Liabilities and Equity | Amount |
|---|---|---|---|
| Cash | 20 | Deposits and Debt | 950 |
| Loans | 980 | Equity Capital | 50 |
| Total | 1,000 | Total | 1,000 |
The bank’s simple equity-to-assets ratio is:
\[ \frac{50}{1000}=5\% \]
Now suppose the bank increases this ratio to 10%. One possible resulting balance sheet is:
| Assets | Amount | Liabilities and Equity | Amount |
|---|---|---|---|
| Cash | 20 | Deposits and Debt | 900 |
| Loans | 980 | Equity Capital | 100 |
| Total | 1,000 | Total | 1,000 |
The key observation is that cash remains at 20 and loans remain at 980. The change occurs on the liabilities-and-equity side: the bank now relies less on debt financing and more on shareholder equity. For example, it could issue 50 in new equity and use the proceeds to repay 50 in debt, leaving the asset side unchanged after both transactions.
The higher equity ratio does not mean that 50 in cash has been locked away and made unavailable for lending. In practice, higher capital requirements may affect banks’ funding costs, shareholders’ required returns, and lending decisions. But these effects arise through financing and risk-bearing incentives, not because equity capital is a segregated cash reserve.
Note: This example uses a simple equity-to-total-assets ratio for illustration; it is not intended to represent every feature of regulatory capital adequacy ratios.
2.4.2 2. Market Value of Equity
The market value of equity is the total stock-market value of a bank’s shares—that is, the amount investors would have to pay, at prevailing share prices, to purchase all of its outstanding equity.
Unlike book equity, market equity reflects investors’ expectations about future developments, including the bank’s profitability, dividend payments, asset quality, and risks. Historically, the market value of bank equity was often higher than its book value because investors expected banks to generate future profits.
However, many major banks have traded at market-to-book ratios below one, particularly in the period following the global financial crisis. The lecture illustrates this with a Financial Times comparison of major global banks as of November 2022.
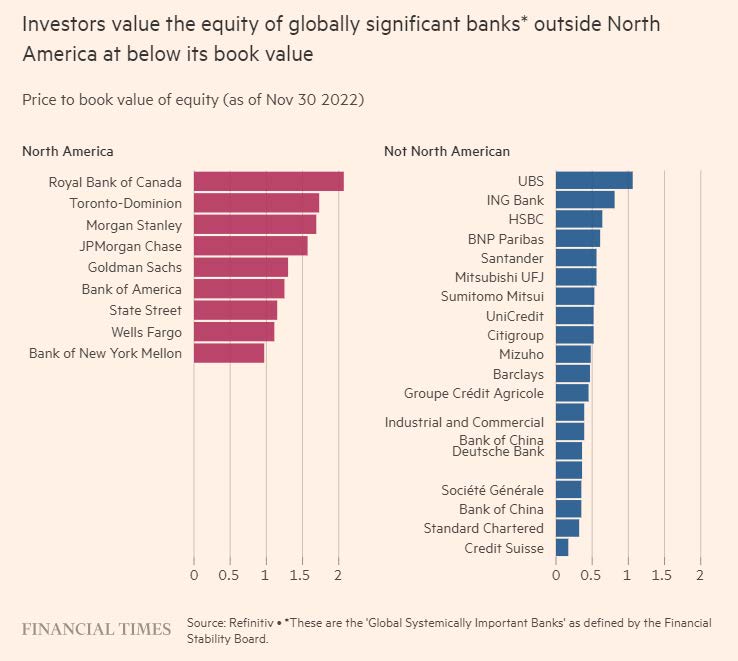
A market-to-book ratio below one can suggest that investors doubt whether reported asset values and expected future earnings fully justify the bank’s book equity. It does not, by itself, establish that the bank is insolvent.
Market valuations therefore provide a useful, though imperfect, signal when evaluating the credibility of a bank’s reported equity capital.
2.5 Banking Regulation
Because banks can encounter both liquidity shortages and solvency problems, governments and banking regulators impose different types of prudential requirements.
2.5.1 1. Liquidity Regulations
The objective of liquidity regulation is to ensure that banks can meet withdrawals and other short-term payment obligations, including during periods of financial stress.
- Reserve requirements. Banks may be required to maintain a minimum fraction of deposits in cash or balances held at the central bank.
- Restrictions on maturity mismatch. Historically, some regulations limited the extent to which financial institutions could finance long-term lending with short-term deposits. For example, mortgage lenders could be required to attract longer-term deposits, while banks funded by demand deposits were restricted to shorter-term loans. Many such restrictions were later removed.
- Requirements for liquid assets. More recent regulatory approaches seek to ensure that banks hold sufficient liquid assets to withstand substantial withdrawals or funding disruptions.
2.5.2 2. Solvency Regulations (Capital Adequacy Requirements)
Solvency regulation, also called capital adequacy regulation, determines the amount of equity capital banks are required to maintain relative to their activities. In general, larger banks and banks with greater risk exposures are expected to maintain more capital to absorb potential losses.
The essential distinction is summarized below:
| Type of Regulation | Main Focus | Primary Objective |
|---|---|---|
| Liquidity regulation | Cash, central bank reserves, and other liquid assets | Ensure that banks can meet short-term payment obligations. |
| Solvency regulation | Equity capital and the bank’s capacity to absorb losses | Reduce the likelihood that losses will leave the bank’s assets worth less than its liabilities. |
Final takeaway: Liquidity concerns a bank’s ability to pay on time, whereas solvency concerns whether the value of its assets exceeds its liabilities. A bank can be liquid but insolvent, or solvent but illiquid. Effective banking supervision must therefore address both dimensions.
网络上很多视频中关于Equity的理解并不准确,可以参考Youtube上 Stanford 大学经济学家Anat Admati的视频。